

Together Loans
4.3

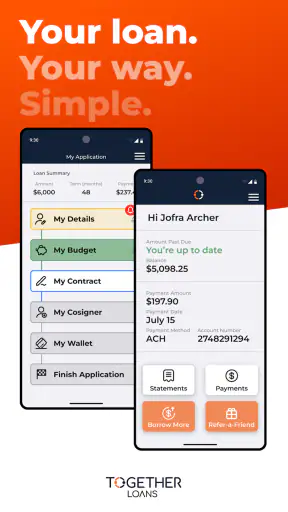
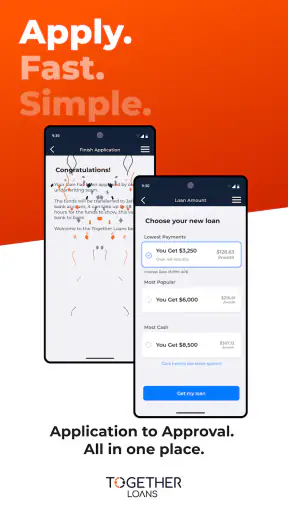
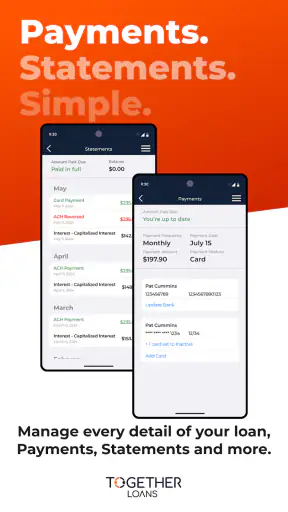
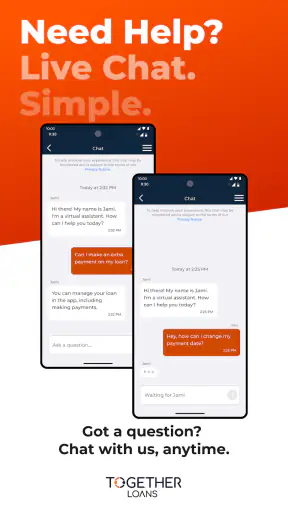
Managing a loan is rarely something I want to do from a browser tab or a pile of emails. That is where Together Loans makes sense. It is a finance app from Transform Credit Inc designed to keep loan management in one place, and my overall impression is that it is most useful as a practical account companion rather than a complete personal-finance system. It does not try to be a budgeting suite, investment dashboard, or general banking replacement. Its value is narrower: helping borrowers stay connected with their loan and handle routine account tasks from a phone.
The app is free to install and is rated for Everyone, which makes the basic proposition easy to understand. It has attracted over 100 thousand installs, with a 4.3 average from around 600 ratings and more than 270 written reviews. Those figures suggest a reasonably positive reception, although I would still treat them as a starting point rather than proof that every borrower will have the same experience.
How Together Loans fits into everyday loan management
When I look at a loan app, I first ask whether it removes a real source of friction. In this case, the answer depends on what you need. If your main concern is checking your loan information, staying aware of repayment activity, and having a single mobile place for the account, Together Loans has a clear purpose. The app’s short description is simply “Together Loans,” while its broader promise is to manage a loan in one place. That focused approach is more useful than a crowded finance app that mixes unrelated services together.
A realistic example would be checking the account before payday. I might open the app to review the current loan details, confirm that I am looking at the correct account, and make sure I understand what needs attention before money leaves my bank account. That small routine can be valuable because it turns loan management into a deliberate check instead of something I only think about after receiving a reminder or noticing an unexpected balance change.
I also see a benefit for people who prefer mobile access over desktop account portals. A phone is usually nearby when a question occurs, so an app can make it easier to check information at the moment I need it. That does not automatically make the financial decision better, but it can reduce the delay between having a question and looking for the answer.
There is an important distinction here: Together Loans is not the same as a broad money-management app. A budgeting service may show spending categories, savings goals, bills, and several financial accounts together. A banking app may combine a current account with transfers and card controls. Together Loans is better judged as a dedicated loan-management tool. If that is the specific task I want to handle, the narrower scope feels sensible. If I want a full picture of my finances, I would still need another service.
The current experience and who benefits most
The strongest audience is an existing borrower who wants a straightforward mobile route to loan information. I would also consider it useful for someone who dislikes managing financial accounts through email links or a mobile browser. The app’s free price removes one obvious barrier, and the Everyone rating makes it approachable for a wide range of users, although financial responsibility still requires an adult level of care and attention.
I would not recommend choosing it simply because it is available in an app store. The right question is whether your loan relationship is supported in the way you expect and whether you prefer using a phone for account management. A person who only needs to make a rare payment may find a normal web portal sufficient. Someone comparing lenders should also avoid confusing account management with the quality or affordability of the underlying loan. An easy interface cannot make an expensive loan inexpensive.
In my experience with finance apps, the most useful habit is to use the app as a checkpoint, not as a substitute for reading loan documents. I would keep the agreement and important messages available elsewhere, then use Together Loans for regular visibility. That approach protects me from relying on a quick screen glance when the original terms contain details that deserve closer reading.
What the current version tells us about the product
The current version is 9.1.2, and the app was released on April 2, 2024. That combination gives the product a relatively recent starting point alongside a mature-looking version sequence. I read that as evidence that the app has gone through ongoing iteration rather than remaining at its initial release state. Still, a version number alone does not tell me exactly which screens or workflows changed, so I would not treat it as proof of a specific new feature.
That is one of the more important details for existing users. A later version can improve stability, adjust navigation, or refine account handling without changing the basic purpose of the app. If I already use Together Loans, I would pay attention to update notes and take a moment to recheck familiar screens after an update. Financial apps deserve that extra care because a small change in labels or navigation can affect how quickly I find account information.
The minimum operating-system requirement is Android 7.0. That is helpful for people using older Android devices, since they do not necessarily need a recent phone to try the app. At the same time, compatibility is not the same as a guarantee of an identical experience across every device. Screen size, system settings, and the age of the phone can still affect how comfortable the app feels.
For someone deciding whether to install it today, I would separate three questions. First, is the phone compatible? Second, is the app intended for the loan I need to manage? Third, do I want a dedicated loan tool or a wider finance dashboard? Answering those questions is more useful than focusing only on the app’s rating or install count.
Small workflows that make it more useful
My first practical tip is to create a repeatable checking routine. Instead of opening the app only when something feels wrong, I would check it at a consistent point around each repayment cycle. The goal is not to stare at the account every day; it is to make loan awareness predictable. A short, regular review can help me notice whether the information I expect is present and whether I need to follow up.
My second tip is to distinguish account visibility from payment confirmation. Seeing a loan screen is not automatically the same as proving that a payment has completed. When I make a payment or expect one to be processed, I would look for the relevant status and retain any confirmation that matters to me. If the wording is unclear, I would use the lender’s official support route rather than guessing from a balance alone.
A third useful workflow is preparing before contacting support. I would open Together Loans first, note the account details and the exact issue, and then describe the problem clearly. For example, “I cannot identify the status of this repayment” is more useful than “the app is not working.” This saves time and helps separate an app-navigation problem from a loan-account question.
I would also avoid using a shared or unlocked phone for sensitive account activity. That is not a unique flaw in Together Loans; it is a basic finance-app precaution. A screen that is convenient when I am alone can become a privacy risk if notifications, recent apps, or an unlocked device expose financial information to someone else.
What existing users may notice as the product evolves
For current users, the biggest likely effect of continued version development is not necessarily a dramatic change in what the app does. It may instead be a smoother route through familiar tasks. That can be positive, but it can also create short-term friction if a button moves or a label changes. I prefer to judge an update by whether I can complete the essential loan workflow with less uncertainty, not by whether the interface looks newer.
The app’s focused design can also be a strength for existing borrowers. Because it is centered on Together Loans rather than trying to become an all-purpose financial hub, I would expect its usefulness to come from clarity and account relevance. The trade-off is that I should not expect it to replace my bank app, budgeting tool, document storage, or broader debt-planning process.
People who have already built a system around email reminders or a browser login may not feel an immediate need to change. In that situation, the app is worthwhile if mobile access makes checking the account easier or more consistent. If the existing method is already clear and reliable, installing another app may add little beyond convenience.
I would be especially cautious about treating convenience as permission to borrow more. A dedicated loan app can make an existing obligation easier to monitor, but it does not remove the obligation. The healthiest use is administrative: understand the account, keep track of what is happening, and respond promptly when action is needed.
Where the app still has limits
The main limitation is scope. Together Loans is not a substitute for a full financial-planning service. I would not choose it when my priority is comparing all debts, building a household budget, tracking investments, or planning long-term savings. Those jobs require tools with a wider view of personal finances, while this app is centered on loan management.
Another possible point of friction is the difference between a clean account view and the complexity of real borrowing situations. A normal repayment routine may be easy to follow, but questions about changes, unusual account activity, or financial difficulty can require human clarification and careful reading of the agreement. I would not assume an app screen can answer every question that arises from a loan contract.
There is also a practical dependency on access. If I lose my phone, change devices, forget login details, or cannot use the app temporarily, I still need an alternative way to manage the account. That is why I would keep important correspondence and account records outside the app. A mobile tool should improve access, not become the only place where I know anything about my loan.
The positive rating is encouraging, but ratings are personal snapshots. A borrower who only needs basic visibility may be delighted, while someone expecting budgeting tools or detailed financial coaching may be disappointed. I would therefore use the 4.3 average as a helpful signal of general satisfaction, not as a guarantee that it matches my own expectations.
How it compares with the usual alternatives
The most obvious alternative is managing the loan through a mobile browser. A browser can be perfectly adequate, especially for occasional use, and it avoids adding another dedicated app. Together Loans has the advantage when I want a more direct, phone-centered route to the account. The browser may be better if I use several financial providers and prefer keeping everything in one place.
A bank app is another alternative, but it serves a different purpose. A bank app is usually stronger for balances, transfers, cards, and everyday spending. Together Loans is more relevant when the loan itself is the account I need to monitor. I would use both rather than expecting either one to cover the other’s role.
Budgeting apps can help me understand whether repayments fit into monthly spending. They are better for planning and comparison, but they may not provide the same direct connection to a particular loan account. My preferred setup would be to use Together Loans for loan-specific visibility and a budgeting tool for the wider household picture, provided I am comfortable maintaining both.
For someone considering a new loan, lender comparison tools and independent financial guidance are more appropriate than Together Loans. This app helps manage an existing relationship; it should not be mistaken for impartial advice about whether borrowing is suitable or which offer is best.
What I would watch before relying on it
I would watch how consistently the app presents the information I need during ordinary repayment periods. A useful loan app should make it easy to identify the account, understand the current status, and recognize when something needs attention. If I repeatedly have to cross-check every detail through another channel, the convenience advantage becomes much smaller.
I would also watch future updates for changes that affect routine navigation. Since the current version is 9.1.2, I would expect the product to continue evolving, but I would judge that evolution by practical outcomes rather than version numbers. Better clarity, dependable access, and less uncertainty would matter more to me than cosmetic redesigns.
Finally, I would watch whether the app remains appropriately focused. Adding useful account tools could improve it, but adding unrelated financial features would not automatically make it better. For this product, restraint may be valuable: borrowers need confidence that they are looking at the right loan information, not a crowded collection of distractions.
My final view is that Together Loans is a sensible choice for borrowers who want a free, dedicated mobile way to stay connected with their loan. Transform Credit Inc has positioned it around a clear everyday need, and the current release history suggests active development since its launch. I like the focused purpose, the accessibility of an Android app that supports Android 7.0 and later, and the possibility of making regular account checks less inconvenient.
I would skip it if I wanted a complete money-management platform, impartial borrowing advice, or a replacement for my bank app. I would also keep backup records and continue reading the actual loan documents, because no mobile interface should be treated as the whole financial relationship. For the right user, though, it can be a useful administrative companion: not a solution to every money problem, but a practical place to keep loan management within reach.
4.3
272.00 Reviews
Pros
- Clear loan comparison helps users review borrowing options in one place.
- Digital application process can save time compared with visiting a branch.
- Useful repayment information supports more informed borrowing decisions.
- May connect applicants with multiple lending partners.
- Convenient access to loan information from a mobile device.
Cons
- Approval and rates depend on personal credit and financial circumstances.
- Some applicants may receive offers with high interest or additional fees.
- Sharing financial details with lending partners raises privacy concerns.
- Not every loan option may be available in all locations.
- Applying can lead to marketing messages from lenders or partners.


